

A company's accounting is based on the double-entry bookkeeping principle , which rests on the premise that every economic action originates from another action of the same value but opposite nature. This system is used to record all of a company's accounting transactions.
What characterizes the double entry method?
This accounting system is governed by three fundamental guidelines:
- No or item without counterpart, or what is the same: there is no debtor without a creditor.
- One or more debit accounts correspond to one or more creditor accounts for the same amount.
- And, related to the previous pattern, sums of quantities entered in the debit must be the same as those entered in the credit. At any time in the accounting cycle.
These guidelines are summarized in the following equation: total assets equals the sum of total liabilities and equity (A = P + PN).
In practice, when is it applied in the accounting of a company?
The double-entry bookkeeping principle is applied to every accounting transaction. And considering that companies are required to record all accounting transactions they carry out—first in the journal and then transferred to the ledger —it is clear that the double-entry system is constantly used in accounting.
We must also keep in mind that every accounting transaction involves two or more accounts, and that every journal entry has at least one debit and one credit entry. Thus, on the Debit side (located on the left side of the journal entry), we will record increases in assets and expenses, as well as decreases in liabilities and equity. Conversely, on the Credit side (right side of the journal entry), we will record decreases in assets, increases in liabilities and equity, and revenues.
The double-entry bookkeeping system is one of the concepts you'll learn when studying the Vocational Training (FP) program in Administration and Finance . This Higher Level Vocational Training program will qualify you to work in a company's accounting department, managing the accounts for different areas.
Double entry system case study
The following examples are very simple, but they serve to illustrate how the double entry system is applied in all accounting operations, otherwise, the recording of operations would be wrong:
Company A charges 3.000 euros (plus 21% VAT) from the sale of goods through a bank transfer.
The entry to be made is:
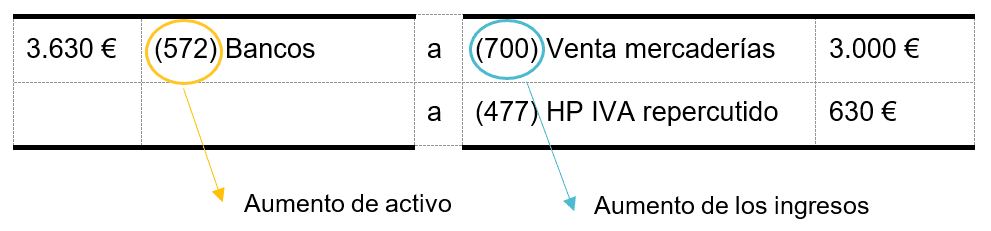
That is, in the Debt we will place the asset accounts, in this case the (572) Banks and, in the Credit, the income: (700) Sale of Merchandise. As can be seen, the sum of the debit and credit amounts coincide (3.630 euros), so the double entry system is fulfilled.
Instead, company A buys goods from a supplier for 5.000 euros (+ VAT) and will pay it in two months.
The entry to be made would be:

On this occasion, in the Debt we will place the expenses and, in the Credit, the increase in liabilities -the pending payment to suppliers, the account (400) Suppliers-. As in the previous example, the sum of the debit and the credit coincides, giving the double entry method.
Is it possible to study accounting at a distance?
Yes, you'll find plenty of videos and tutorials online, but if you're looking to follow a structured curriculum and earn an official qualification authorized by the Ministry of Education and Vocational Training, the Higher Level Vocational Training Certificate in Administration and Finance is an option. At ILERNA Online , you can study at your own pace, whenever, however, and wherever you want, with the support of instructors , learning materials, and weekly video lessons . You can also take the final exams for each subject in the Spanish provincial capital nearest to you.