

The margin between supply and demand has been very tight since 1996. Even in 1996, 1997, 2000, and 2001, supply was insufficient, leading to stock shortages. In the early 80s, an ounce of gold was worth US$850 . The price plummeted over the next two decades, reaching levels of US$250 per ounce in 1999, which has influenced mining companies' decisions regarding new exploration.
From a supply perspective, production fell by 4% in 2018, the largest decline in the last 65 years. This justifies the expectation that gold production will be cut by 30% in 2020, a factor that will put downward pressure on prices. It is important to understand that supply is highly inelastic. It takes between four and seven years to begin extracting gold once a mine has been geographically located.
In any case, gold is one of the alternatives for seeking refuge in the face of instability in equity markets. With intermediation margins that can reach double digits, it's an investment that can be diversified, as it can be acquired through investment funds, jewelry, gold bars, and coins. This contrasts with other financial assets that are more static in terms of their investment supply.
Gold: role of Central Banks

One of the traditional factors that has caused sharp drops in the price of gold has been central banks. The reason for this behavior can be explained by the high interest rates they faced. Since owning gold itself does not generate any return, central banks during periods of restrictive monetary policy would sell or lend gold in exchange for other countries' debt. High interest rates made the opportunity cost of holding gold in reserves excessive, and therefore banks were inclined to increase the supply and flood the market with gold.
The current situation is radically different. Interest rates are very low , and there are no prospects for significant increases. As a result, the opportunity cost has been greatly reduced, and if we add to that the costs of carrying out the transaction through debt and the potential risk of investing long-term with a completely flat yield curve, there are sufficient reasons to begin to think that central banks will limit their gold sales as much as possible. It is even reasonable to think that they could become net buyers due to factors such as inflation protection, which we will explain later.
Mass purchase by China
China continues to massively purchase American debt , and the US economy is set to continue posting budget deficits. Initial estimates (which are nothing more than estimates) suggest that reconstruction after the recent hurricanes could be more expensive than the Iraq War itself, which took place decades ago. One of the few alternatives offered as a source of diversification for Chinese monetary authorities has been gold.
Currently, banks hold around 20% of the world's known gold stock. This is a very significant volume, and if they were to begin repatriating some of the borrowed gold , it could put considerable upward pressure on the price of an ounce. In any case, this is a good time to start taking positions in this financial asset with the aim of generating returns on savings in the medium and long term. However, this is certainly not without risk, given the inherent characteristics of this unique investment alternative that gold currently represents.
Demand factors
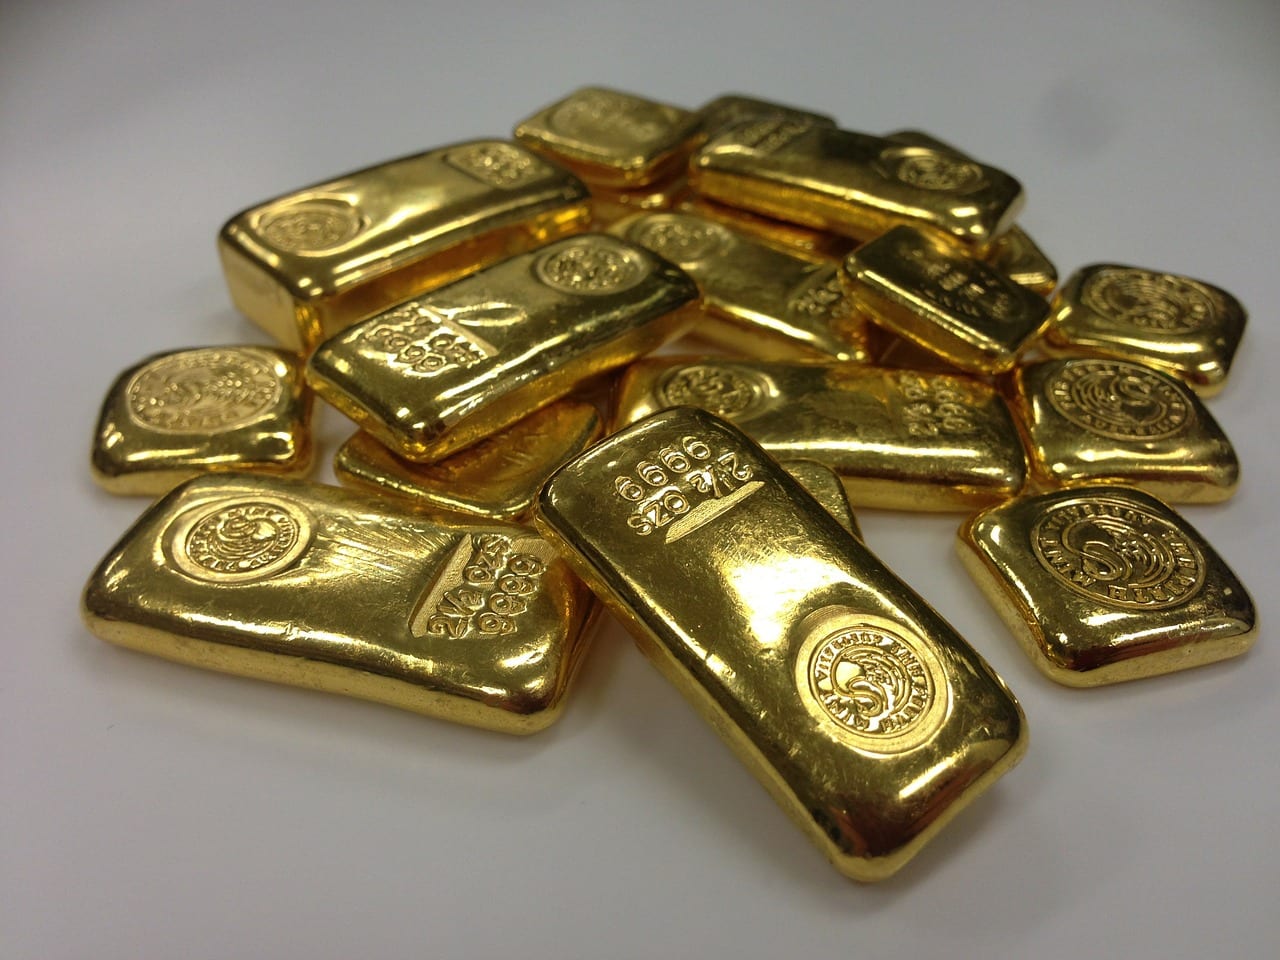
India continues to demonstrate remarkable strength in its demand . In addition to the traditional sectors (jewelry and dentistry), mining companies themselves have also increased their demand for gold for investment purposes. These companies have been selling their production before extraction through forward contracts. They were selling gold in advance because:
- Some companies they speculated after years of steep falls in gold in the 80's and 90's with expectations of bear markets.
- Other companies rely on the futures market to be able to fix (“lock-up”) the price level prior to the exploitation of the mine and reduce risks.
- Benefit from opportunity cost of having your premium money on your balance sheets for higher interest rates.
- The sector of jewelry and dentistry it has remained inelastic. Its production levels are not affected by variations in the price of the ounce.
- Faced with the rise in gold, companies have to buy back part of sales (buy-backs). This is one of the key drivers of the price rally to the $ 460 per ounce levels we are currently at.
- China it has also seen demand for gold increase as a result of having authorized the possibility of buying gold for investment and for speculative purposes.
Another important factor is the World Gold Council. The WGC has allowed that through the London Stock Exchange in London and in the US (and is being studied for the Australian Stock Exchange) it is possible to invest in gold directly and not in gold mining companies. The Spanish investor has the opportunity to take part in this market through SG warrants.
Safe-haven asset factors
It's no secret that gold's value isn't tied to the financial strength or credit rating of its owner. It's a liability-free asset, perfect for investing in situations with high levels of debt and a risk of bubbles . There's a general consensus that a housing bubble exists globally. While Spain has witnessed meteoric housing growth, it's not an isolated phenomenon. London and the US are maintaining double-digit growth rates. American families have debt levels exceeding 80%, and gold is clearly the best safe haven in case of a bubble bursting.
Another phenomenon putting pressure on markets is the increased use of derivatives due to the relative protection offered by financial instruments such as Credit Default Swaps . Warren Buffett himself said: “In our view, derivatives are financial weapons of mass destruction that carry risks that, while not explicitly stated, are potentially lethal.”
With high leverage
This increase in leverage, driven by both the performance of the real estate sector and the use of derivatives, coupled with the fact that 65% of US debt is held by foreign entities (compared to 50% historically), suggests a search for uncorrelated assets such as gold. However, positions should always be taken with great caution due to the volatility this important financial asset may exhibit from this point forward. Price corrections cannot be ruled out, which could justify an even more aggressive bet on this quintessential safe-haven asset.
Gold performs well in both inflationary and deflationary scenarios and is an asset uncorrelated with the dollar's performance. For investors anticipating a depreciation of the greenback, it represents a potential source of returns. Interestingly, for euro-denominated investors, gold's appreciation has been minimal, trading sideways with high volatility due to Brexit.
Demand for gold funds

There are several aspects that must be taken into account to value this investment from these moment prices. And among which the following stand out, which we expose below to be analyzed by small and medium investors, with the aim of making their operations profitable:
Appreciation of the local currencies of producing countries with respect to the dollar; countries such as South Africa, Australia and Canada had their costs in local currency, with income in dollars.
Specific events involving major industry players , such as Goldfield's hostile takeover bid for Harmony's, were received negatively by the market. This explains why, in the coming months, crude oil prices may rise simultaneously with major currencies appreciating across the board (although this gap is narrowing after the recent increases in the price of oil).
The special valuation that the yellow metal is having by minority investors compared to another class of much more conventional options, such as the purchase and sale of shares on the stock market or investment funds themselves. In a new scenario in which new investment formulas appear year after year, some of them clearly innovative. So that the products with which the savings can be made profitable at this time are raised. Although some with clear risks in their positions.