

This time, we wanted to briefly review two terms widely used in the world of finance and economics for their incredible usefulness in providing results about companies and determining the viability of investing in a particular project: NPV and IRR. These two tools can help you make a lot of money or steer clear of poor investment options.
What are NPV and IRR
Net Present Value (NPV) and Internal Rate of Return (IRR) are two powerful financial tools that allow us to evaluate the potential profitability of different investment projects. In many cases, investment in a project is not seen as an investment but rather as an opportunity to launch another business due to its profitability.
Now, let's give a brief introduction to NPV and IRR, these financial concepts separately, so you can see how they are calculated and which is the best option depending on the results you want to know and the possibilities that NPV and IRR offer.
What is NPV
Net Present Value (NPV ) is a financial tool used to calculate the difference between the money coming into a company and the amount invested in a product or project, to determine if it can generate profits for the company.
The NPV includes an interest rate called the cutoff rate, which is used for constant adjustments. This cutoff rate is determined by the person evaluating the project, in conjunction with the investors.
The NPV cut-off rate can be:
- The interest that is in the market. What you do is take a long-term interest rate that can be easily taken out of the current market.
- Rate in the profitability of a company. The interest rate that is marked at that time will depend on how the investment is financed. When it is done with capital that someone else has invested, then the cut-off rate reflects the cost of borrowed capital. When it is done with its own capital, it has a direct cost to the company but it gives the shareholder profitability
When the rate is chosen by the investor
This can be any rate of your choice.
It is usually carried out with the minimum profitability that the investor intends to have and will always be below the amount in which the investment will be made.
If the investor wants a rate that reflects the opportunity cost , the person forgoes receiving money to invest in a particular project.
How can NPV be applied
To understand how to use NPV, we have a formula: NPV = Net Present Value – Investment . We already know what NPV is, and NPP is the net present value, or in other words, the company's cash flow.
This method should always be used with the updated net profit, not the projected net profit, to ensure accurate calculations. To determine the net profit ( NPB), you must apply a discount rate (DR) . This represents the minimum rate of return and is calculated as follows.
If the rate is higher than the BNA this means that the rate has not been satisfied and we have a negative NPV. If the BNA is equal to the investment, this means that the rate has been met, the NPV is equal to 0.
When the BNA is higher, it means that the rate has been met and, in addition, a profit has been made.
So for us to quickly understand
When the latter scenario occurs , it means the project is profitable and can proceed. When the project breaks even, it's still profitable because the TD profit is included, but caution is advised. When the former scenario occurs, the project is not profitable , and other options must be explored.
You must choose the project that gives us the best additional profit.
Advantages of NPV
One of the main advantages , and the reason it's one of the most widely used methods, is that it standardizes net cash flows at the present time. NPV, or Net Present Value, can reduce the amounts of money generated or contributed to a single unit. Furthermore, positive and negative signs can be introduced into the cash flow calculations corresponding to inflows and outflows without altering the final result. This is not possible with IRR, where the result is significantly different.
However, NPV has a weak point , which is that the rate used to discount the money may not be entirely understandable or even debatable for many people.
Now, when it comes to homogenizing the interest rate, it is one of the best options with a very high reliability.
What is IRR and how is it used
What is IRR? The IRR, or internal rate of return , is the discount rate applied to a project that ensures the net present value (NPV) is at least equal to the initial investment. When we talk about IRR, we're referring to the maximum discount rate a project can have to be considered viable.
To calculate the IRR correctly, you'll need the investment amount and the projected net cash flow. Whenever you calculate the IRR, you should use the NPV formula provided above, but replace the NPV value with 0 to obtain the discount rate . Unlike NPV, a high discount rate indicates that the project is not profitable, while a lower rate suggests profitability. The lower the discount rate, the more profitable the project.
Is this type of method reliable?
You should know that the criticisms that this method has suffered are many due to the degree of difficulty it has for many people. However, nowadays it has already been possible to program in spreadsheets and the most modern scientific calculations also come with this option incorporated. They have achieved that they can be done in seconds.
Even so, returning to the most used and the main one, it is done when in a certain project it has been possible to make reimbursements or disbursements that are having, not only at the beginning but during the useful life of the same, either because the project has been having losses or new investments have been included.
When to use VAN or TIR

Both the NPV and the IRR are two indicators widely used by professionals, but each of these tools has a specific use when using them. And it is convenient to know when to use NPV and when to IRR and how to assess the results you get from both.
Therefore, here we are going to leave you in a practical way when to use each of them.
When to use the VAN
Net present value (NPV) is the metric many companies use to standardize their net cash flows. In other words, it reduces all the amounts of money generated or contributed to a single figure. Furthermore, it's the tool they use to determine if a project is profitable; in other words, if there are returns based on the investment made.
To do this, they use the formula NPV = BNA-Investment. Thus, if the investment is greater than the BNA, the figure obtained from the NPV is negative; and if it is the opposite it means that there is a profit.
So when should it be used? Well, when you want to know if your net profit is really adequate or if you are having losses. In fact, this should be used on an annual basis, although the figures can actually be drawn at any time of the year (but always with data up to that date).
What is the NPV formula?
Is the next:
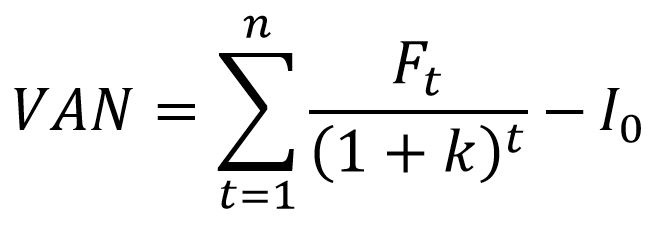
Where:
- Ft are the cash flows in each period (t).
- I0 represents the initial investment.
- n is the number of periods being calculated.
- k is the discount rate.
What is TIR and what is it for?
Turning now to the IRR, you must bear in mind that, as we have told you, it is not the same as the NPV, they are two totally different tools that measure similar things, but not the same.
The IRR value is used to assess whether a project is profitable or not, but nothing more . The formula used is the same as that for NPV, but in this case the NPV is 0, and the goal is to determine the discount rate, or the investment.
Thus, the higher the value that comes out in that formula, it means that the project is less profitable. But the lower it is, the more profitable it is.
When is it used?
And when should it be used? In this case, it's the best indicator for assessing the profitability of a specific project. In other words, it gives you a concrete figure, but this cannot be compared to the figure for another project, especially if they are different, because more variables come into play (for example, one project might start slowly and then take off, or it might be more long-lasting).
In general, both the NPV and the IRR indicate whether a project can be carried out or not, that is, whether benefits will be obtained with it or not. There is no one better tool or another to do this, since both the NPV and the IRR complement each other and investors take into account the results of both before making a decision.
How to know if the IRR is good

After all that we have told you, there is no doubt that the indicator that can have the most weight when it comes to knowing whether a project is good or not is the internal rate of return, that is, the IRR. But how do you know if the IRR is good or not in a project?
When evaluating this rate, that is, the IRR, it is necessary to take into account two very important factors. These are:
- The size of the investment. That is, the money that is going to be put to carry out that project.
- The projected net cash flow. That is, what is estimated to be achieved.
To calculate the IRR of a business, the same formula as the NPV is used ; however, instead of calculating the NPV, the discount rate is determined. Therefore, the IRR formula would be:
NPV = BNA - Investment (or discount rate).
Since we do not want to find the NPV, but rather the Investment, the formula would look like this:
0 = BNA - Investment.
BNA would be the net cash flow while the I is what we must solve for.
For example, imagine you have a five-year project. You invest 12 euros and, each year, you have a net cash flow of 4000 euros (except for the last year, which is 5000). Thus, the formula would be:
0 = 4,000 / (1 + i) 1 + 4,000 / (1 + i) 2 + 4,000 / (1 + i) 3 + 4,000 / (1 + i) 4 + 5,000 / (1 + i) 5 - 12,000
This gives us the result that i is equal to 21%, which tells us that it is a profitable project, and that the IRR is good, if it is really what is expected to be obtained. Remember that the lower the value, the more profitable the project you are analyzing will have.
And this is where the expectation of profitability comes into play. For example, imagine you have a project that looks very profitable and is attractive. And that you hope to get a profitability of at least 10% for him. After doing the numbers, you see that the project is going to offer you a return of 25%. That is much more than you expected, and therefore it is something attractive and that is telling you that the IRR is good.
Instead, imagine that instead of that 25%, what the IRR offers you is 5%. If you have scored a 10, and it gives you a 5, your expectations drop a lot, and unless you have thought otherwise, that project would not be so good (and it would not have a good IRR) based on your investment.
Generally speaking, a safe, risk-free business will yield a good, but low, IRR. However, when you invest in businesses that do involve some risk, provided you act sensibly and knowledgeably, you can expect a higher and therefore better IRR. For example, right now, technology projects or those related to primary sectors (agriculture, livestock, and fishing) can be profitable and beneficial.
Botton line
The IRR or the internal rate of return is a very reliable indicator when it comes to the profitability of a specific project. When a comparison of the internal rates of return of two different types of projects is carried out, the possible difference that may exist in their dimensions is not taken into account.
Now, after learning all this, we ask ourselves , is it easy to understand? Do we already know what NPV and IRR are?
At the beginning VAN and IRR may be two terms that confuse you a bit but for the performance of your company and above all so that you do not lose money they are of the utmost importance, since thanks to this you can know when a project is really profitable that you can invest in it or if you have the option between several projects, you can know which project is more profitable.
It also allows you to know when a project is unprofitable and what the difference is that you will stop earning.
Therefore, both NPV and IRR are complementary financial tools and can provide us with valuable data on the companies or projects in which we are willing to invest, ensuring that we always have 100% of the profits in the projects we want to undertake.
Find out what ROE or Return on Equity is:
